Dubai gold rates climb for second day with 24K at Dh491.75
Silver slips amid shifting dollar and rate expectations
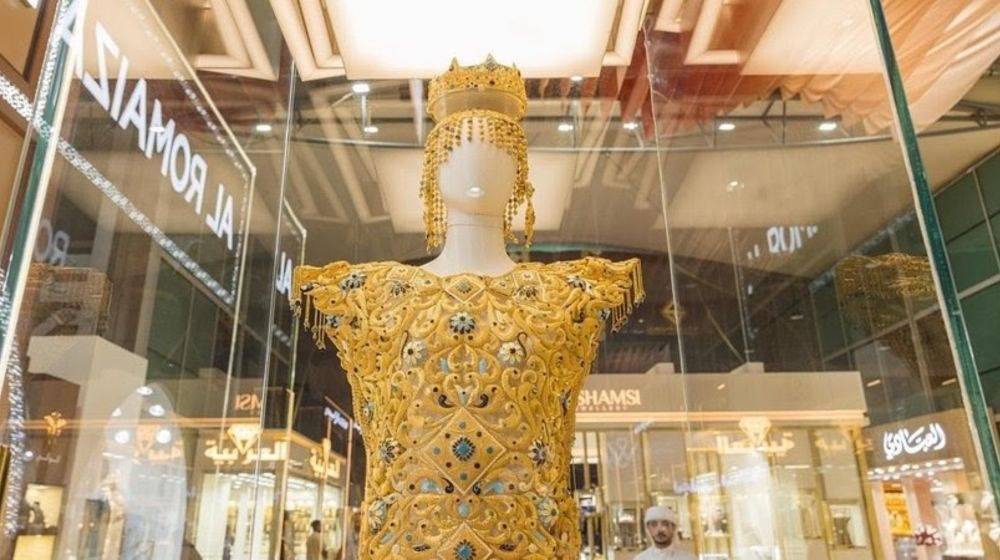
DUBAI – Dubai's gold market remained firmly in focus on Friday as retail jewellery prices moved higher, reflecting gains in international bullion markets and renewed investor interest in the precious metal.
Gold continues to attract buyers across the emirate, where competitive pricing and tax advantages make it one of the world's leading destinations for jewellery purchases. The latest increase follows a volatile trading week shaped by currency movements, interest rate expectations and geopolitical developments.
According to the Dubai Jewellery Group's suggested retail rates, all major gold categories recorded gains from the previous session, pushing prices close to levels seen at the beginning of the week.
Dubai gold rates
The Dubai Jewellery Group listed 24K gold at Dh491.75 per gram on Friday, up Dh4.25 from Dh487.50 on Thursday. The 22K rate increased to Dh455.50 from Dh451.50, while 18K gold climbed to Dh374.25 from Dh371.00 per gram.
The latest rise follows Wednesday's prices of Dh485.25 for 24K, Dh449.25 for 22K and Dh369.25 for 18K. On Tuesday, rates stood at Dh487.00, Dh451.00 and Dh370.50 respectively, while Monday opened the week with 24K at Dh492.75, 22K at Dh456.25 and 18K at Dh375.00 per gram.
Friday's increase marks the second consecutive daily rise after Wednesday's dip, although prices remain slightly below Monday's opening levels.
Global markets
Internationally, spot gold slipped 0.6 percent to $4,076.53 an ounce in early trading on Friday, while US gold futures for August delivery eased 0.4 percent to $4,074.20. Despite the decline, spot gold remained on course for its first monthly gain in five months, with prices up about 1.7 percent during July.
The US dollar rebounded around 0.3 percent after suffering its biggest single-day fall since January 2023 on Thursday. A stronger dollar generally weighs on gold by making the metal more expensive for buyers using other currencies.
Markets also continued to digest the US Federal Reserve's decision to leave interest rates unchanged earlier this week. Investors are assessing expectations for the next policy move as higher interest rates typically reduce the appeal of non-yielding assets such as gold.
Attention also remained on geopolitical developments after a drone strike hit gas vessels at Egypt's Mediterranean port of Damietta, raising fresh concerns over shipping through the Suez Canal during the ongoing US-Iran conflict. The wider regional situation, including risks surrounding the Strait of Hormuz and its importance for global oil exports, has kept safe-haven demand for gold firmly in the spotlight.
Other precious metals
Among other precious metals, spot silver fell 0.8 percent to $58.48 an ounce. Platinum declined 1.7 percent to $1,631.77, while palladium slipped 0.8 percent to $1,294 per ounce.
Despite Friday's losses, both platinum and palladium remained on track to post monthly gains as investors continued to monitor shifts in global demand, monetary policy expectations and developments across energy markets.